Proper insurance and bonding are essential for business credibility and risk management, requiring careful selection of policies tailored to your specific industry and needs.
Securing the right insurance and bonding is a critical step in establishing a trustworthy and resilient business. These financial safeguards protect your company from unforeseen liabilities and provide your clients with essential peace of mind. Navigating the requirements can seem complex, but a methodical approach will ensure you obtain the correct coverage.
Thinking a license bond is about your work quality
Most contractors believe the Arizona Contractor License Bond guarantees their project performance. It doesn't. This bond is a financial guarantee to the state that you will follow licensing laws, pay owed taxes, and cover certain public liabilities from your business operations. The part most applicants underestimate is the personal credit check. Underwriters review your credit to assess the risk you'll default on the bond's financial obligation, not your skill as a contractor. A low score doesn't automatically disqualify you, but it directly impacts your premium rate and the speed of approval.
- The bond protects the public and state, not your client's project outcome.
- Your personal credit score is the primary factor determining your bond premium.
- You are personally liable for any claims paid by the surety on your bond.
Understanding the Difference: Insurance vs. Bonding
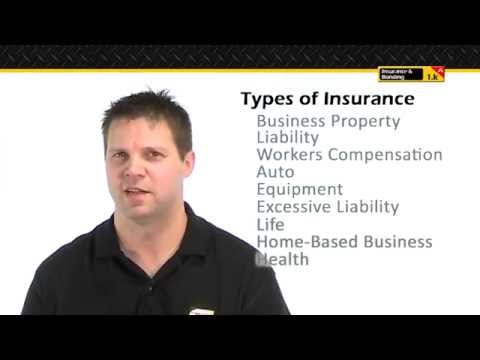
While both are risk management tools, insurance and bonding serve distinct purposes. Business insurance primarily protects your company from losses due to events like accidents, lawsuits, or property damage. A bond, however, is a three-party agreement that guarantees your business will fulfill its contractual obligations, providing financial recourse to your client if it fails to do so. For a detailed overview of common business insurance types, you can refer to the U.S. Small Business Administration’s guide.
Assessing Your Business Risks
Before contacting providers, conduct a thorough risk assessment. Identify the specific liabilities inherent to your industry, the value of your assets, and the requirements of your clients or local regulations. This foundational analysis is crucial for determining the types and levels of coverage you need, rather than making arbitrary or insufficient choices. A common mistake is overlooking contractual requirements from larger clients, which often mandate specific coverage limits or additional insured endorsements that standard policies may not include.
Researching and Selecting Providers
Look for insurers and surety companies with strong financial ratings and expertise in your specific industry. Obtain multiple quotes to compare coverage terms and premiums. It is highly advisable to consult with a licensed commercial insurance broker who can interpret policy language and help you navigate the nuances of different offers. When comparing quotes, pay close attention to exclusions and sub-limits, as these often vary significantly between carriers and can leave you exposed in critical areas.
The Application and Underwriting Process
Be prepared to provide detailed information about your business operations, financial history, and safety protocols. The underwriting process for bonds, in particular, will scrutinize your company’s creditworthiness and professional track record. Maintaining organized financial records and a clean business history will significantly streamline this phase. For contractors, surety underwriters typically evaluate your work-in-progress schedule and accounts receivable aging reports, so having these reconciled and current will accelerate approval.
To ensure a smooth application process, gather these key documents in advance:
- Business financial statements (last 2-3 years)
- Business license and relevant professional licenses
- Details of past projects and client contracts
- A resume outlining key personnel experience
- Any existing safety manuals or operational procedures
- Certificate of insurance from your current carrier, if applicable
Maintaining Your Coverage
Once secured, proactively manage your policies and bonds. Review your coverage annually or whenever your business undergoes a significant change, such as expansion, new services, or increased revenue. Promptly renew your bonds to avoid lapses that could breach client contracts and damage your professional reputation. Set calendar reminders at least 60 days before renewal dates, as last-minute renewals can trigger additional underwriting scrutiny or result in non-renewal if your financial picture has shifted.