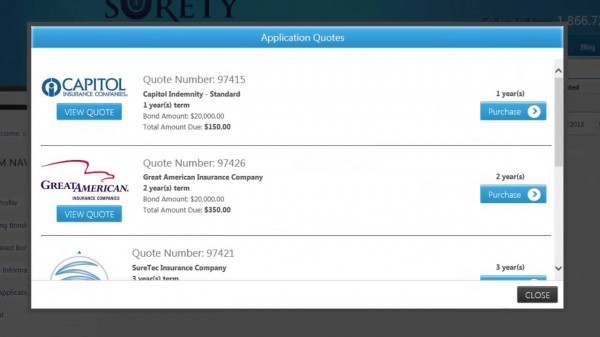
Contractor bonds in Oregon are a type of surety bond required by the state to protect consumers from financial loss due to a contractor's failure to comply with licensing laws.
If you are a contractor in Oregon, you are likely familiar with the requirement to obtain a contractor bond. This financial guarantee is a key part of maintaining your license and operating legally within the state. It protects your clients by providing a recourse if you fail to adhere to contracting laws and regulations.
In Oregon, the specific bond amount is mandated by the Construction Contractors Board (CCB). This bond is a legal requirement for licensure, not an optional form of insurance. It serves as a safeguard for the public, ensuring that contractors fulfill their contractual obligations and adhere to state building codes. The bond amount is set by statute and may be adjusted periodically, so checking current CCB requirements before renewal is essential.
When a valid claim is filed against your bond, the surety company will investigate and, if the claim is substantiated, provide financial compensation to the claimant. As the bonded contractor, you are then legally obligated to reimburse the surety company for the full amount paid out, plus any associated fees. This system underscores the bond’s role as a credit instrument rather than traditional insurance. In practice, a single substantiated claim can make future bonding more expensive, as sureties factor claim history into premium calculations.
Maintaining an active and valid bond is absolutely critical for your business continuity. Allowing your bond to lapse or having excessive claims filed against it can result in severe penalties from the CCB, including license suspension or revocation. Proactive bond management is a fundamental aspect of professional risk management for contractors. A lapse in coverage, even for a few days, can trigger a license hold that halts all active projects until proof of continuous coverage is restored.
To ensure you remain in good standing, consider the following best practices for managing your contractor bond:
- Set a calendar reminder for your bond renewal date well in advance of its expiration.
- Review any claim notices immediately and communicate promptly with your surety provider.
- Keep detailed records of all project contracts, communications, and completion certificates.
- Understand the specific terms and conditions of your bond agreement thoroughly.
- Monitor your credit score regularly, as personal credit is a primary factor in bond underwriting and premium rates.
The process of obtaining a bond typically involves a surety company evaluating your personal and business financial health, including credit history and professional experience. For more detailed information on Oregon’s licensing and bonding regulations, you can refer to the official Oregon Construction Contractors Board website.
While the upfront cost is a factor, a contractor bond is a vital investment in your company’s credibility and legal compliance. It signals to potential clients that you are a serious professional committed to ethical business practices. Ultimately, it is a foundational component for building a reputable and sustainable contracting business in Oregon.
The license is not the bottleneck your bond is
Most contractors focus on passing the trade exam, but the real delay is the surety bond underwriting. The state requires the bond, but the surety company requires a deep review of your personal credit, business financials, and project history. A low credit score or thin business file can trigger requests for additional collateral or personal indemnity, stalling the entire license application. What usually slows this down is applicants submitting incomplete financial statements or underestimating how their personal credit impacts the premium.
- Order your bond before your exam to lock in your rate and avoid last-minute underwriting surprises.
- Prepare two years of business and personal tax returns upfront—missing documents are the most common cause for delay.
- A credit score below 650 will likely require a financial statement and may increase your bond premium by 25-50%.